Responding 24 hours a day

Guide

Does insurance cover water damage? An honest answer

An honest guide to water damage and homeowners insurance in Texas: sudden and accidental leaks, gradual leaks, and flood water. We document; your insurer decides.

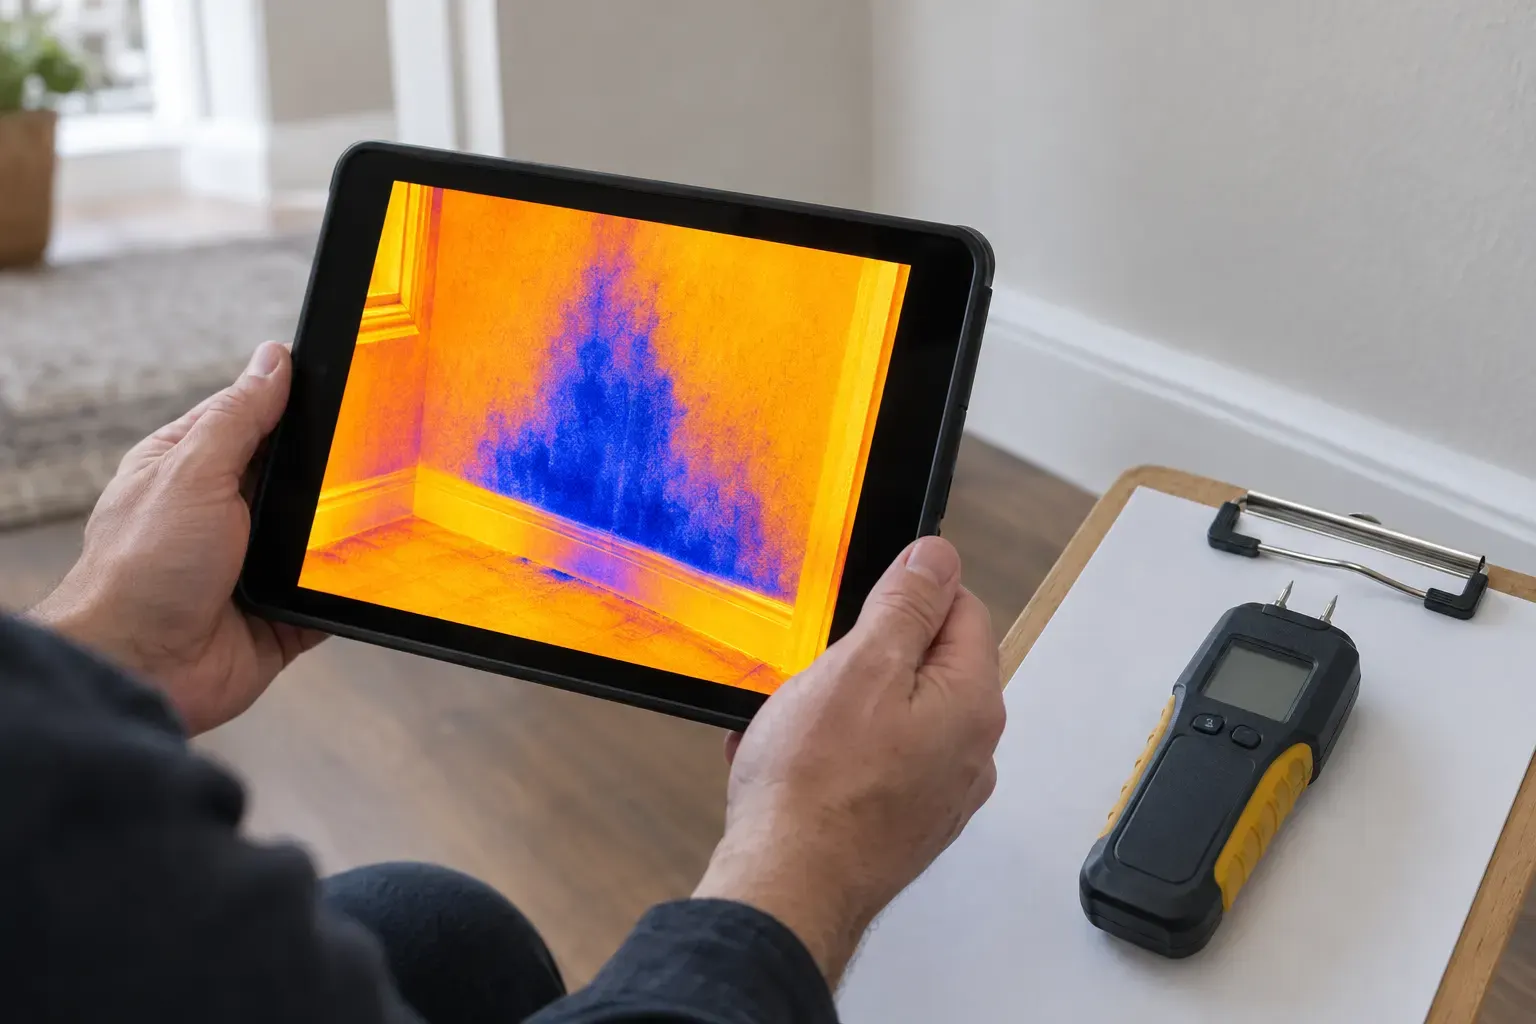
A tablet showing a moisture scan beside a moisture meter
Exhibit AReference / Guide

It depends on your policy and on where the water came from. The Texas Department of Insurance says most home policies cover sudden and accidental water damage, such as a burst pipe or a broken washer hose, but not damage from a leak that has been dripping for a long time. Flood water from outside is usually excluded and needs a separate flood policy.

Sudden and accidental water damage

According to the Texas Department of Insurance, most home policies cover water damage that is sudden and accidental: a leak or overflow that happens suddenly, not one that has been dripping for a long time. Examples include a burst pipe or a failed washing machine hose.

Gradual leaks

A slow leak that went on for weeks or months is a different matter. The TDI home insurance guide lists a continuous water leak among the things most policies do not cover.

Flood water from outside

TDI explains that flood damage comes from rain or a body of water rising over dry ground and into the house, while water damage comes from pipes and appliances inside. FEMA's FloodSmart program says most homeowners and renters insurance does not cover flood damage; flood coverage is a separate policy, often through the National Flood Insurance Program.

What you can do

  • Stop the water and make the home safe.
  • Take photos and video before repairs.
  • Make enough temporary repairs to keep the damage from getting worse, and keep receipts.
  • Tell your insurance company as soon as you can.
  • Read your policy or call your agent with coverage questions.

Where 111 fits

We mitigate the damage and document it carefully, so your adjuster can review it. We do not decide coverage, interpret your policy, or negotiate your claim, and we never promise that an insurance company will pay. Those decisions belong to your insurer under your policy.

This guide is general information, not insurance or legal advice. Updated November 2026.

FAQ

Related questions

Is a slab leak covered by insurance?

Coverage for slab leaks varies by policy. Some policies treat access to the leak and the resulting water damage differently from the pipe repair itself. Ask your agent and read your policy.

Should I wait for the adjuster before starting mitigation?

TDI advises making enough repairs to keep the damage from getting worse. Mitigation is that kind of work. Document the damage first, and tell your insurance company as soon as you can.

Open a file

Water or fire damage? Talk to a team member.

We respond 24 hours a day. Send the short form and a team member will call you back within 90 minutes. We come out, look at the damage, and give you an honest assessment. There is no pressure to sign anything on the first visit.

What goes in your file

  • 01An honest assessment. A team member looks at the damage in person and tells you plainly what we see and what we recommend.
  • 02A written scope before work starts. You know what we plan to do and why, and you can share it with your insurance company.
  • 03Photo and video documentation. Every affected area is recorded before, during, and after the work.
  • 04Moisture readings and drying records. Logged on each visit until materials reach their drying goals.
  • 05A room-by-room contents inventory. When contents are packed out, each item is listed, photographed, and tracked.
  • 06A closeout file. Photos, readings, inventory, scope, and the signed completion record in one place.

See our process

Intake sheetForm 111-A

Request a call back

Tell us where and what happened. Required fields are marked.

Send the form and a team member will call you back within 90 minutes. We use your details only to respond to this request. See our privacy notice.

Request a call back